A savings challenge gives your money a job to do, week by week, without a complicated budget spreadsheet. The 52-week version is the one most people start with: you save $1 in week 1, $2 in week 2, and so on up to $52 in week 52, which adds up to $1,378 by the end of the year. Small, steady deposits make saving feel doable instead of overwhelming.
This article walks you through the tools you need, the popular variations, the step-by-step setup, and the mistakes that trip people up. You will also find printable tracker tips and a realistic timeline so you know exactly what you are committing to.
Key Takeaways
- Traditional 52-week challenge: save $1 in week 1 up to $52 in week 52, totaling $1,378.
- Pick a weekly amount that fits your income, not the other way around.
- Keep challenge money in a separate savings account so you are not tempted to dip in.
- If larger end-of-year deposits feel daunting, run the challenge in reverse.
- Missing a week is not a failure; pick up where you left off and keep going.
1. What is a 52-Week Savings Challenge?
A 52-week savings challenge is a structured method to save money over a year, building consistent habits. The traditional version involves saving increasing amounts each week: $1 in week 1, $2 in week 2, up to $52 in week 52. Completing it totals $1,378. The beauty is that you can customize the amounts to fit your income and goals, making saving less daunting and more achievable.
2. What You Need to Start Your Savings Challenge
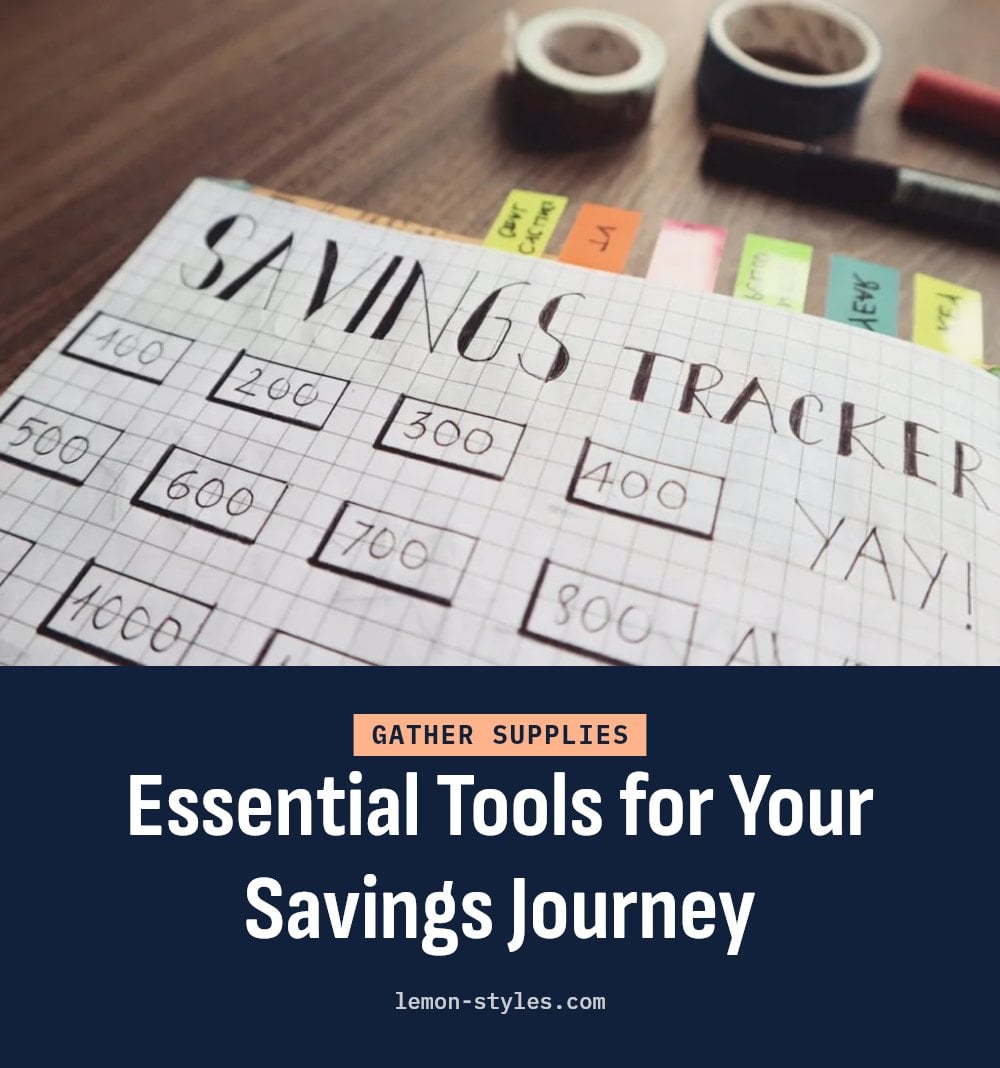
To get started, you need a few simple tools:
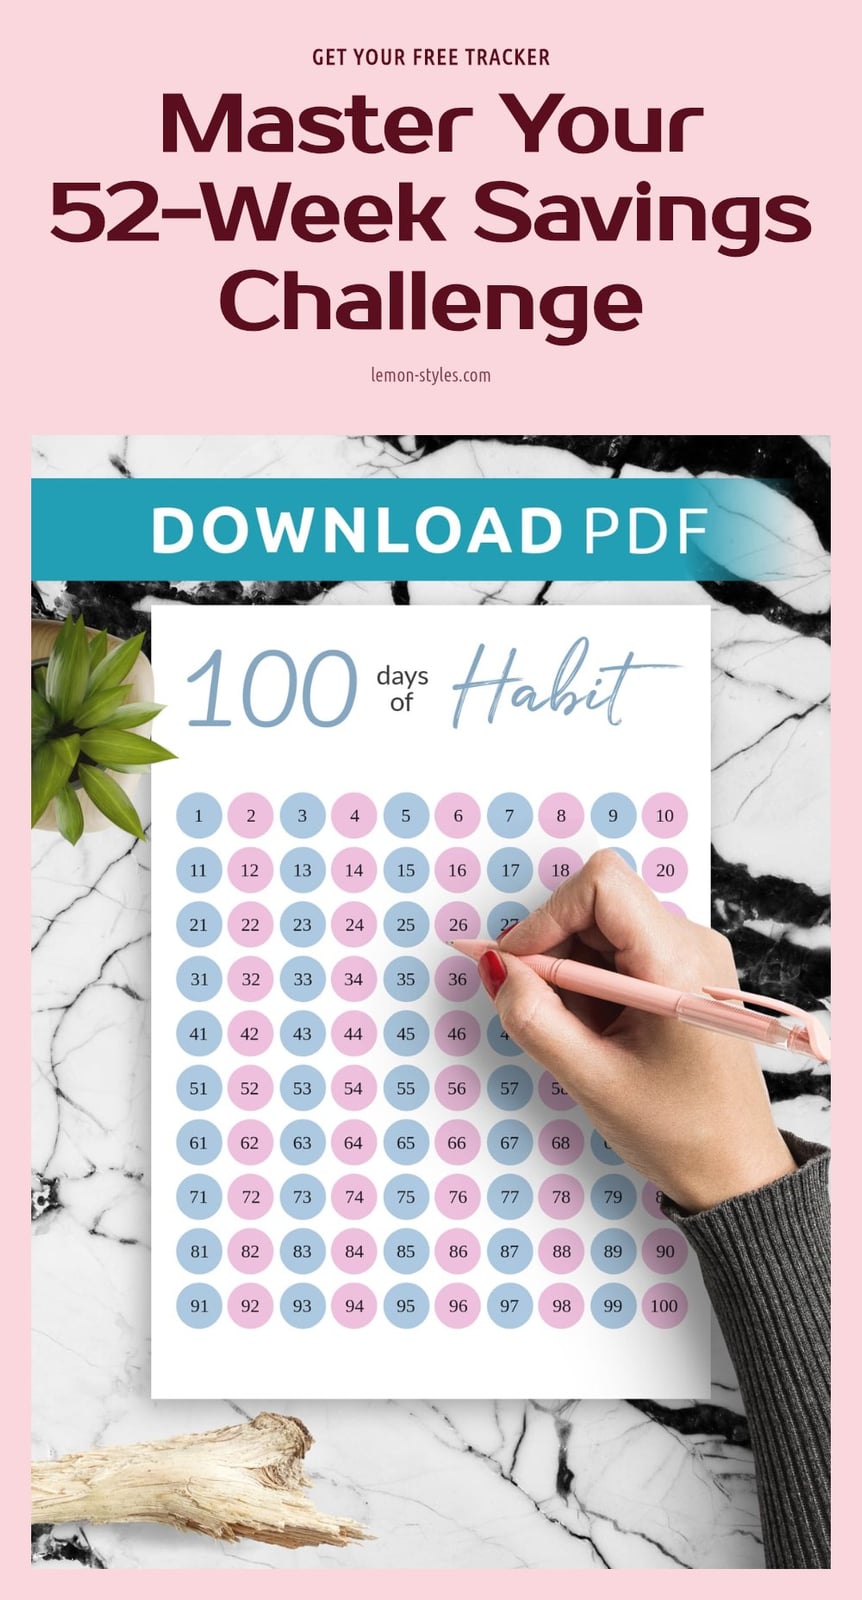
- Printable savings tracker or chart: This provides visual motivation as you mark each week’s progress.
- Separate savings account: Keeping challenge money distinct from everyday spending helps avoid temptation and may earn interest.
- Jar or piggy bank: Useful if you prefer a cash-based challenge for a tangible feel.
3. Popular Savings Challenge Methods to Try
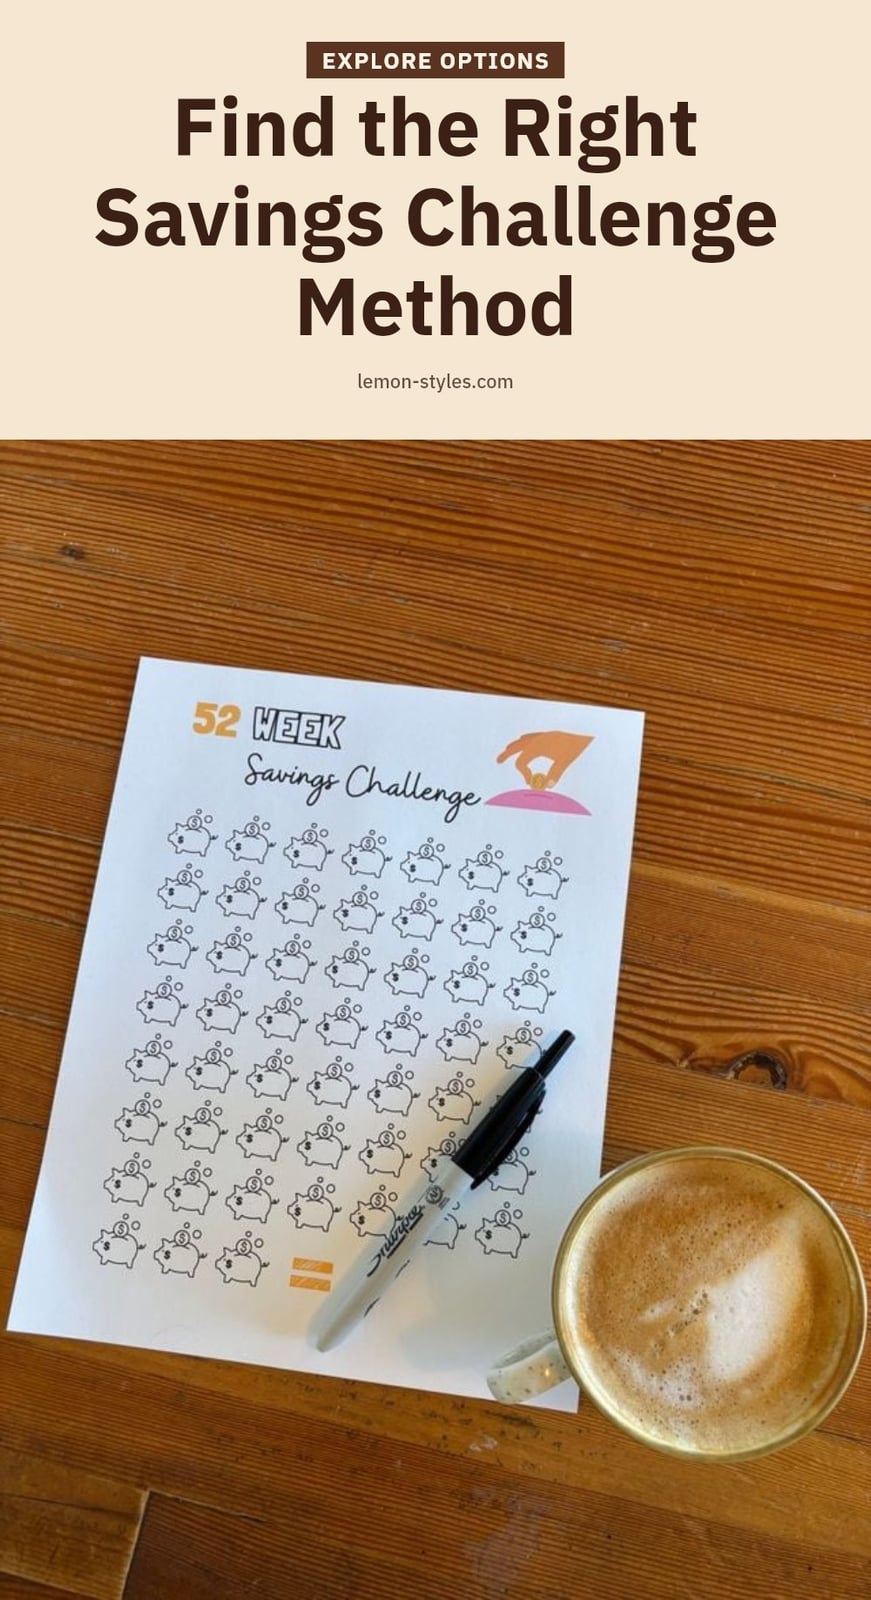
There are several popular methods to choose from, each with its own rhythm.
Traditional 52-Week Challenge
Save increasing amounts each week: $1 in week 1, $2 in week 2, and so on. By week 52, you have $1,378. Tip: This works well if you expect your income to grow over the year.
Reverse 52-Week Challenge
Start with the largest amount ($52 in week 1) and decrease each week. This makes the end of the year easier, especially around the holidays. Caution: The first few weeks require discipline, so ensure you have the cash flow.
Fixed Amount Challenge
Save the same amount every week, such as $25. This offers predictability and is easy to automate. Tip: Multiply your weekly amount by 52 to see your total before starting.
Other Fun Challenges
- No-spend challenge: Pick a day or week to spend nothing on non-essentials, putting the saved money aside.
- Round-up challenge: Round up purchases to the nearest dollar and transfer the difference to savings.
4. Step-by-Step: How to Master Your 52-Week Savings Challenge
- Define your goal: Set a clear, motivating reason for saving, like an emergency fund or a vacation. This keeps you committed when motivation dips.
- Choose a realistic challenge: Pick a method that matches your income and lifestyle. If the traditional challenge feels too steep at the end, try the reverse version.
- Use a visual tracker: Print a chart or use a spreadsheet. Marking off each week gives a sense of accomplishment and helps you stay on track.
- Automate transfers: Set up automatic transfers from your checking to your savings account on the same day each week. This removes the temptation to skip.
- Be flexible: If unexpected expenses arise, adjust your weekly amount or pause for a week. Just pick up where you left off without guilt.
5. Common Savings Challenge Mistakes and How to Avoid Them
Mistake: Choosing an overly ambitious challenge. Picking a challenge that requires large weekly payments you cannot afford leads to discouragement and quitting. Pick a realistic amount that fits your current income, even if it means saving less overall.
Mistake: Not having a clear purpose. Without a specific goal like an emergency fund or a vacation, the saved money is too easy to spend. Define your reason before you start, and write it on your tracker.
Mistake: Forgetting to track progress. Skipping the visual check reduces motivation. Use a printable chart, an app, or a spreadsheet to mark each week’s deposit.
Mistake: Keeping money in an easily accessible account. If the savings sit in your checking account, you will be tempted to dip in. Move the money to a separate savings account as soon as you deposit it.
6. Best Tips for Staying Motivated and Successful
Celebrate small milestones. When you hit $100 or $500 saved, reward yourself with a small treat that does not undo your progress. A coffee or a movie keeps the momentum going.
Don’t get discouraged by a missed week. If you skip a deposit, just pick up where you left off. You do not need to make it up; consistency matters more than perfection.
Consider the reverse challenge. If saving $52 in week 52 feels daunting during the holiday season, start with $52 in week 1 and decrease each week. The payments get easier as the year goes on.
Review your progress periodically. Every quarter, check if the challenge still fits your budget. If your income changes, adjust the weekly amounts to keep saving realistic.
7. How Long Does a Savings Challenge Take?
A 52-week savings challenge takes one full year to complete. You contribute a set amount each week for 52 weeks. The total you save depends on the method you choose. The traditional 52-week challenge saves $1,378 by the end of the year. Consistency across those 52 weeks is what makes the challenge work.
8. When to Seek Professional Financial Advice
A savings challenge should never cause financial strain. If meeting the weekly deposits means you cannot pay bills or cover essentials, pause the challenge and talk to a financial advisor. If you are dealing with debt, prioritize professional debt counseling before starting any savings plan. For complex goals like investing or retirement, a certified financial planner can help you build a strategy that fits your full financial picture.
9. Frequently Asked Questions
Can I start a savings challenge at any time of the year?
Yes. A 52-week challenge is simply 52 consecutive weeks, so you can begin in any month. Many people like starting in January because it lines up with fresh goals, but a mid-year start works just as well. Just keep an eye on which weeks land during expensive months so you can plan ahead.
What if I can’t afford the weekly amount in a 52-week challenge?
Lower the amounts or switch to a fixed weekly deposit you can comfortably cover. The challenge is a framework, not a rule, and adapting it to your income is the whole point. If deposits would stop you from paying bills or buying essentials, pause and speak with a financial advisor before continuing.
Is it better to save cash or use a bank account for a savings challenge?
A separate savings account is usually the stronger choice because the money is out of easy reach and may earn interest. Cash in a jar can be motivating for some people since you see it grow, but it is easier to dip into and carries a small risk of loss. Pick whichever you will actually stick with.
How do I stay motivated during a long savings challenge?
Use a visual tracker you mark each week, and celebrate milestones like $100 or $500 saved with a small treat that does not undo your progress. Automating transfers also removes the daily decision. When a week slips by, log it and move on rather than abandoning the whole challenge.
What is the 365-day penny challenge?
It is a daily challenge where you save a small amount that increases each day over the year, starting with pennies and growing gradually. It suits people who prefer a daily habit over a weekly deposit. The total is modest, so many people pair it with a larger goal or treat it as a warm-up.
10. Final Thoughts
My recommendation: start with the reverse 52-week challenge if your budget is tighter in November and December, and go traditional if you would rather ease in gently. Either way, set your goal before week 1 and keep the money in a separate account. Expect it to take the full year, with 52 weekly deposits and a total of $1,378 on the traditional track. Some weeks will feel easy and some will not, and that is normal. Consistency matters far more than perfection, so give yourself room to adjust when life gets expensive.
This article offers general information about savings challenges and is not financial, legal, or medical advice. If you are dealing with debt, financial stress, or a persistent money problem, speak with a qualified financial advisor or debt counselor who can review your situation.